Categories
Buying a home, Clarksville TN Real Estate, Selling a homePublished November 10, 2026
Is Your Low Mortgage Rate Keeping You in the Wrong House? What Clarksville Move-Up Buyers Need to Knows
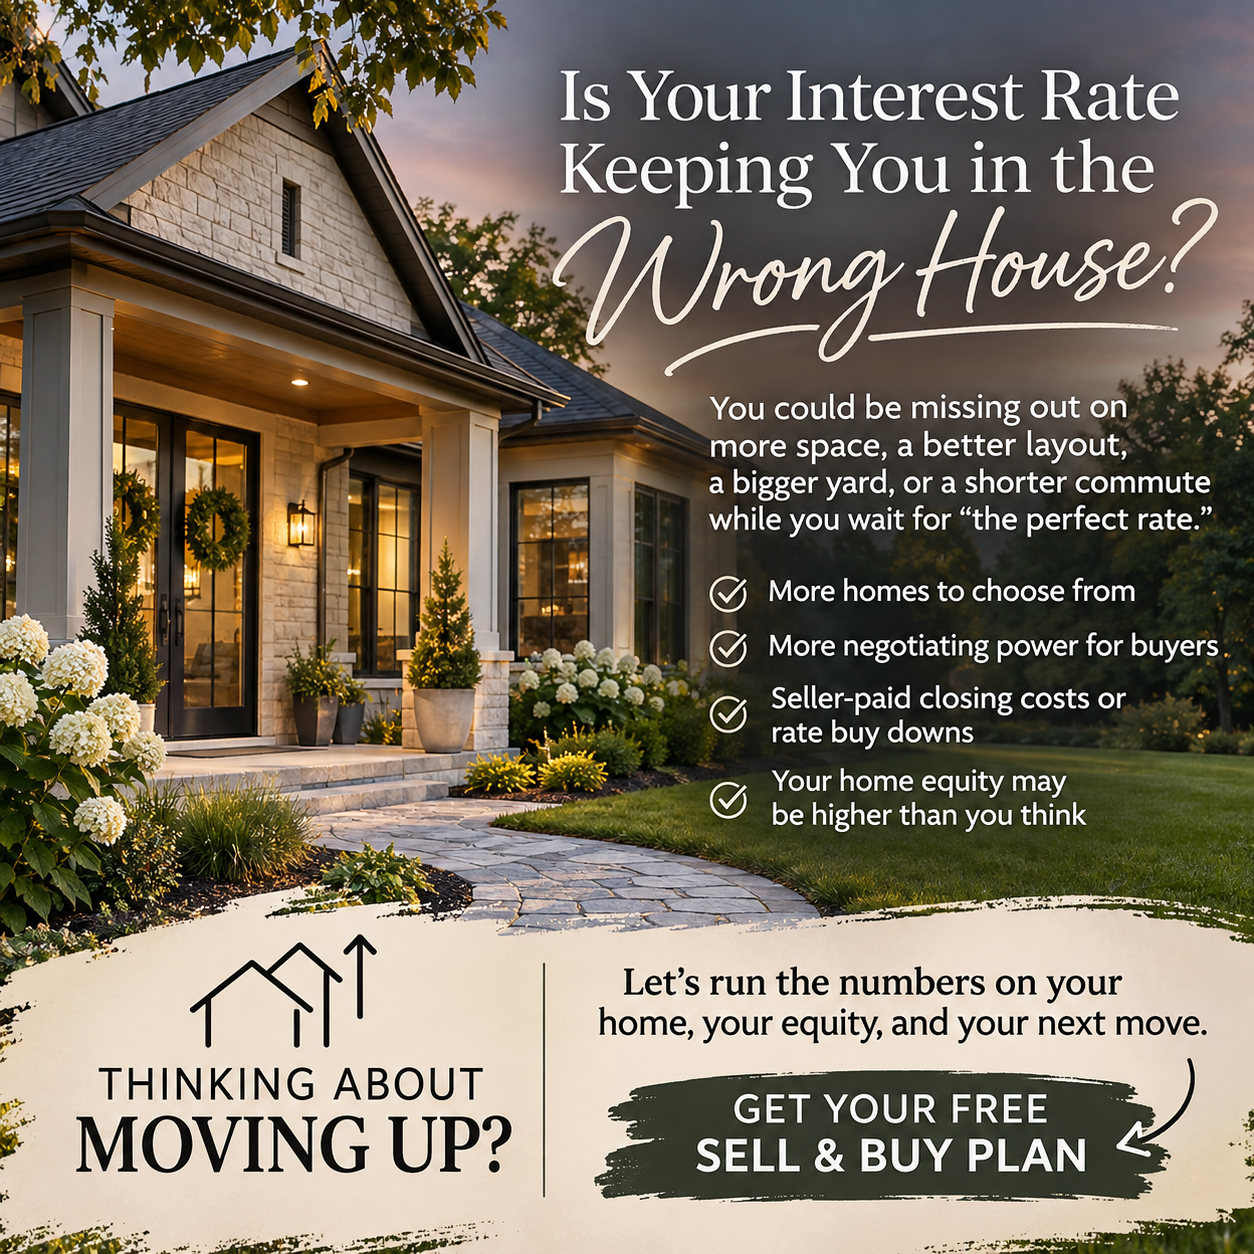
Is Your Low Mortgage Rate Keeping You in the Wrong House? What Clarksville Move-Up Buyers Need to Know
If you've thought about selling your home and buying something bigger, chances are you've had the same conversation with yourself:
"I would love to move, but I just can't give up my interest rate."
Maybe you purchased your home when rates were historically low. Maybe you locked in a mortgage in the 3%, 4%, or even low 5% range. Now, the thought of taking on a higher interest rate makes moving seem financially irresponsible.
I understand the hesitation. But here's a question worth asking:
What is staying in a home you've outgrown actually costing you?
For many homeowners in Clarksville, Tennessee, the decision to move isn't just about mortgage rates. It's about growing families, changing lifestyles, needing more space, and finding a home that better fits the next chapter of life.
And sometimes, waiting for the perfect interest rate means putting your life on hold.
The Mortgage Rate Trap: Why So Many Homeowners Aren't Moving
The real estate industry has been talking about mortgage rate lock-in for several years. Homeowners with low mortgage rates are hesitant to sell because replacing their existing mortgage means financing their next home at a potentially higher rate.
This has created a situation where many homeowners who would otherwise be ready to move are staying put.
According to Inman's October agent survey, 45% of agents reported thinner listing pipelines compared with the previous year. Meanwhile, the National Association of REALTORS® reported year-over-year inventory growth of 4.6%.
What does this mean for Clarksville homeowners?
It means the market is changing, and there may be opportunities for both buyers and sellers who are willing to look beyond the interest rate.
What If Your Current Home No Longer Fits Your Life?
Think about what has changed since you purchased your current home.
- Your family has grown, and you need another bedroom.
- You're working from home and need a dedicated office.
- The kids need more room to play.
- You want a larger yard or a different neighborhood.
- Your commute has changed.
- You're ready for a different lifestyle or a home that better fits your long-term plans.
These aren't small things. Your home impacts your everyday life.
Instead of focusing exclusively on what a higher mortgage rate might cost, consider what another two or three years in your current home might cost you in space, convenience, comfort, and quality of life.
The goal isn't to convince you to move. It's to make sure you're making the decision based on the entire financial picture.
Today's Market May Offer More Negotiating Opportunities
One thing move-up buyers sometimes overlook is that they're not just selling a home. They're also buying one.
That creates an interesting opportunity.
If you're selling in a market with limited inventory, your home may attract attention from buyers looking for exactly what you have to offer.
When purchasing your next home, increased inventory can give you more choices and potentially more negotiating power.
Depending on the property and seller's circumstances, you may be able to negotiate:
- Seller-paid closing costs.
- A mortgage interest rate buydown.
- Repairs or other concessions.
- A more favorable purchase price.
A seller-paid rate buydown can be especially worth exploring. In some transactions, the seller contributes money toward temporarily reducing the buyer's mortgage interest rate.
For example, a 2-1 buydown may reduce the interest rate by two percentage points in the first year and one percentage point in the second year before returning to the permanent note rate.
These options aren't guaranteed, but they're worth discussing when evaluating your next purchase.
The Real Math: What Would Moving Actually Cost?
Before deciding that moving is too expensive, let's look at your actual numbers.
A move-up analysis should include four important pieces:
1. Your Current Home's Market Value
What could your home realistically sell for in today's Clarksville market? Your home's value may have changed significantly since you purchased it.
2. Your Available Equity
After accounting for your mortgage payoff and estimated selling expenses, how much money could you potentially bring to your next purchase?
3. Your Next Mortgage Payment
What would your payment look like at today's interest rates? We'll compare different purchase prices, down payments, and financing scenarios.
4. Potential Seller Concessions
Could you negotiate seller-paid closing costs or a rate buydown to help make your next home more affordable?
When you put all four pieces together, you may discover that moving is more attainable than you originally thought.
Should You Wait for Mortgage Rates to Drop?
This is probably the biggest question I hear from homeowners considering a move.
Unfortunately, nobody can predict exactly where mortgage rates will be six months or a year from now.
Waiting could mean lower rates, but it could also mean more competition from buyers, changes in home prices, and fewer opportunities to negotiate.
And remember: if rates decrease significantly, more buyers may reenter the market. That could change the negotiating environment for both buyers and sellers.
Rather than trying to time the market perfectly, I recommend making a decision based on your financial position, your family's needs, and what the numbers look like today.
You can always explore refinancing opportunities in the future if rates become more favorable and refinancing makes financial sense. But you can't get back the time spent waiting for the perfect market.
Let's Build Your Clarksville Sell & Buy Plan
If you've been thinking about moving but feel stuck because of your current mortgage rate, I'd love to help you explore your options.
As a local real estate broker serving Clarksville, Fort Campbell, Oak Grove, and surrounding communities, I work with homeowners navigating exactly these kinds of decisions.
I'll put together a complimentary, no-obligation Sell & Buy Plan that includes:
- An estimated market value for your current home.
- Your potential equity after selling expenses.
- Estimated payments on homes that fit your needs.
- Opportunities to negotiate seller-paid closing costs or rate buydowns.
- A strategy for coordinating the sale of your current home with your next purchase.
You don't have to commit to moving. You just need to know what your options look like.
Your interest rate is important. But it shouldn't automatically determine where your family lives.
Ready to find out what moving up could look like?
Contact Angie McCormick at The McCormick Group RE.
Call or message me and put "MOVE UP" in the message. Let's run the numbers before you decide to stay put another year.
The right move starts with the right information.
Angie McCormick
Broker/Owner
The McCormick Group RE
angie@forsaleinclarksville.com
(615) 772-1709
Angie McCormick
Broker/Owner | The McCormick Group
or another way