Categories
Buying a home, Clarksville TN Real EstatePublished November 3, 2026
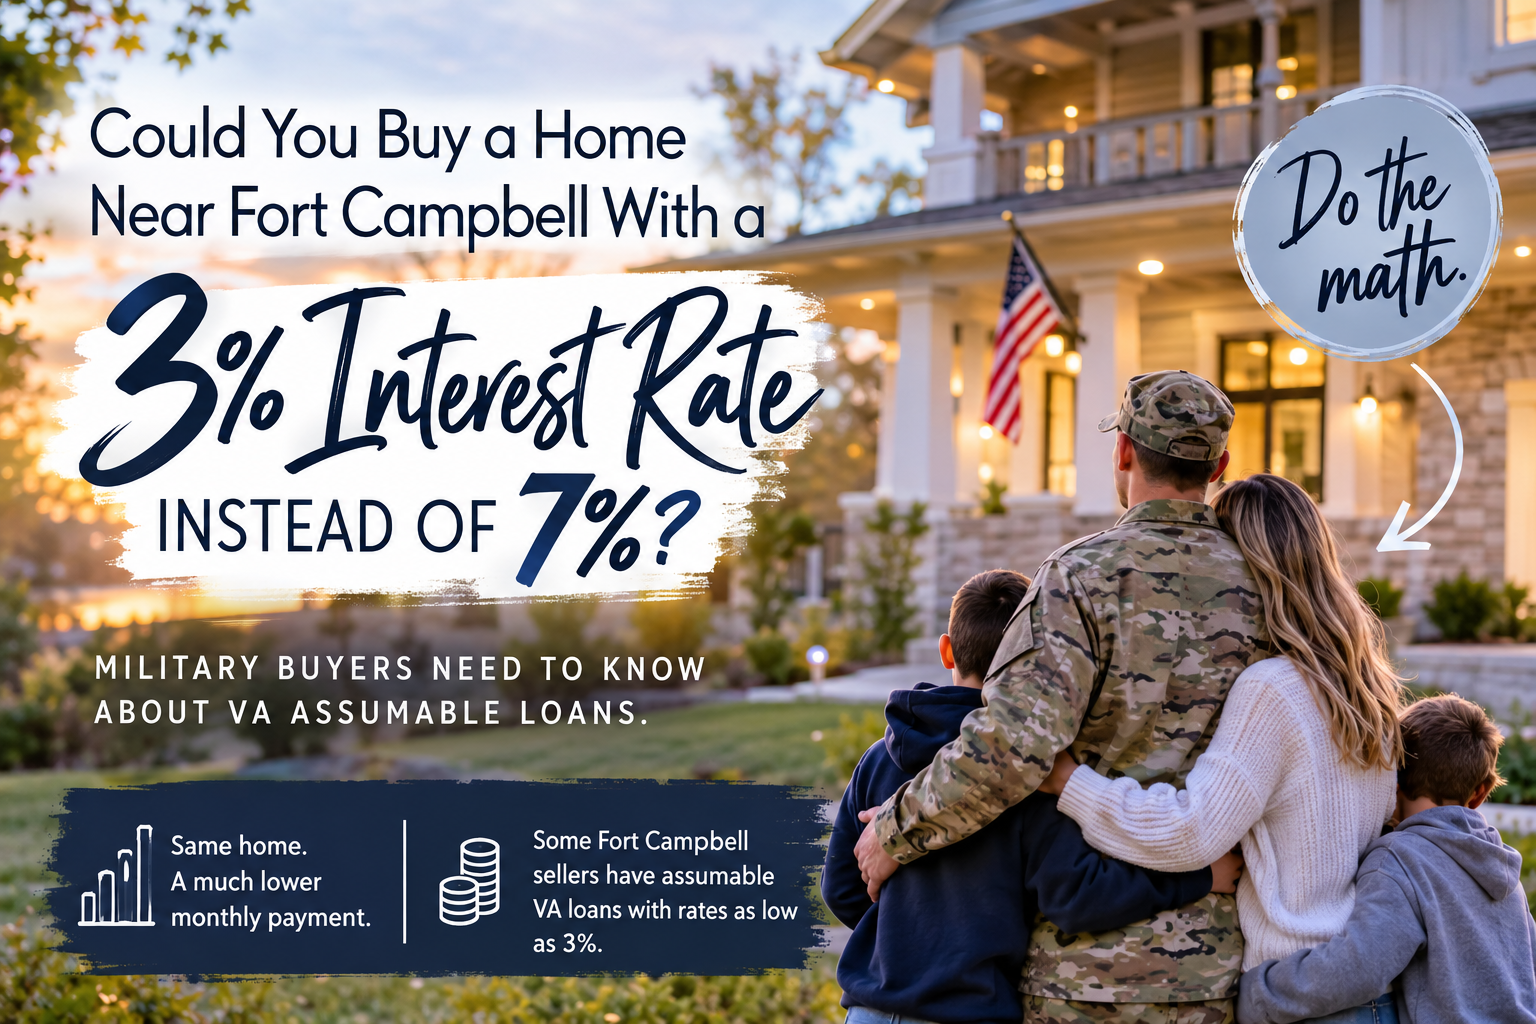
Could You Buy a Home Near Fort Campbell With a 3% Interest Rate Instead of 7%? Military Buyers Need to Know About VA Assumable Loans
If you're a military family preparing for a PCS move to Fort Campbell, you may be looking at today's mortgage rates and wondering how you're going to make the numbers work.
Here's something you might not know: You may be able to purchase a home and take over the seller's existing VA mortgage, including their original interest rate.
It's called a VA loan assumption, and for the right buyer, it could mean substantial monthly savings.
With some Clarksville and Fort Campbell-area homeowners still holding VA mortgages with interest rates around 2.5%–3.5%, this is a financing strategy worth exploring before you purchase your next home.
Let's break down how it works.
What Is a VA Assumable Loan?
Unlike many conventional mortgages, VA loans are generally assumable.
This means a qualified buyer may be able to take over the seller's existing VA mortgage instead of obtaining an entirely new mortgage at current market rates.
For example, imagine a homeowner purchased a home several years ago when mortgage rates were significantly lower.
They currently have:
- Remaining mortgage balance: $350,000
- Interest rate: 3%
- Original loan type: VA
Instead of obtaining a new mortgage at 7%, a qualified buyer may be able to assume that existing 3% mortgage.
The buyer essentially steps into the seller's existing loan, subject to lender approval and the terms of the assumption.
And that interest rate difference can make a tremendous impact.
How Much Could You Actually Save?
Let's look at a hypothetical example.
Assume you're financing $350,000 over 30 years.
| Interest Rate | Monthly Principal & Interest |
|---|---|
| 3% | $1,476 |
| 4% | $1,671 |
| 5% | $1,879 |
| 6% | $2,098 |
| 7% | $2,329 |
The difference between a 3% and 7% interest rate is approximately $853 per month.
That's more than $10,000 per year!
Imagine what your family could do with that additional money:
- Pay down debt.
- Build your emergency savings.
- Put more money toward retirement.
- Save for your next PCS move.
- Enjoy more financial flexibility.
These numbers reflect principal and interest only. Property taxes, homeowners insurance, HOA fees, and other expenses are additional.
Actual savings will depend on the remaining loan balance, loan term, and assumption terms.
The Biggest Catch: What About the Seller's Equity?
This is where things get a little more complicated.
When you assume a VA loan, you're only taking over the seller's remaining mortgage balance. You're still responsible for paying the difference between that balance and the home's purchase price.
Let's say you find a home listed for $425,000.
The seller has:
- Purchase price: $425,000
- Existing VA mortgage balance: $350,000
- Existing interest rate: 3%
That leaves a $75,000 equity gap.
You would need to come up with that $75,000 through cash, eligible secondary financing, or another acceptable arrangement.
This is why assumable loans aren't necessarily the right fit for every buyer.
However, if you have savings, proceeds from selling another home, or access to an appropriate secondary financing option, it may be worth exploring.
Can Any Buyer Assume a VA Loan?
Yes! You do not necessarily have to be a veteran to assume an existing VA loan.
However, there are important distinctions.
A qualified non-veteran may be able to assume the loan, but the original veteran seller's VA entitlement may remain tied up in that mortgage until the loan is paid off or other applicable VA entitlement substitution requirements are met.
For a veteran buyer, substituting their available VA entitlement may be possible if the requirements are satisfied.
The lender or loan servicer must approve the assumption, and the buyer must meet applicable credit and underwriting requirements.
It's important to understand these details before entering into a purchase agreement.
Are VA Assumable Loans Available in Clarksville and Near Fort Campbell?
Absolutely worth investigating!
Clarksville, Tennessee, and the surrounding Fort Campbell communities have a significant military population.
Many homeowners purchased their properties when mortgage rates were historically low. Some of those homeowners may still have existing VA loans that could potentially be assumed.
The challenge is finding them.
Not every seller knows their mortgage is assumable, and not every listing advertises this financing opportunity.
That's why having a real estate agent who understands VA assumptions and knows how to identify potential opportunities can make a difference.
When working with military buyers, I encourage looking beyond the listing price and considering the financing attached to the property.
Sometimes the best deal isn't necessarily the least expensive house. It's the house with the best overall financial opportunity.
What Should You Do Before Buying a Home With an Assumable VA Loan?
If you're considering this strategy, here are a few steps I recommend:
- Get prequalified. Talk with a lender experienced in VA loan assumptions.
- Determine your available cash. Understand how much you can put toward the seller's equity.
- Identify potential properties. Look for homes where the seller may have an existing VA mortgage with a below-market interest rate.
- Understand the timeline. Loan assumptions can take longer than traditional mortgage financing, so plan accordingly.
- Review the seller's loan details. Confirm the remaining balance, interest rate, monthly payment, remaining term, and assumption requirements.
The right lender is especially important here. Not every mortgage lender regularly handles VA loan assumptions.
Moving to Fort Campbell? Let's Find Your Opportunity.
If you're receiving PCS orders to Fort Campbell, relocating to Clarksville, or considering a move to Oak Grove, Kentucky, don't overlook VA assumable loans.
You could potentially save hundreds of dollars every month by taking over an existing mortgage instead of obtaining a new loan at today's interest rates.
I work with military families relocating throughout the Clarksville and Fort Campbell area, and I'm always looking for creative ways to help buyers make the most of their home purchase.
Want to know which homes might have assumable VA loans?
Reach out to me with the word ASSUME, and let's talk about what opportunities might be available.
Your next home might come with a much better interest rate than you think!
Angie McCormick
Broker/Owner | The McCormick Group RE
Serving Clarksville, TN | Fort Campbell, KY | Oak Grove, KY and surrounding communities
Disclaimer: VA loan assumptions are subject to lender/servicer approval, applicable VA requirements, and buyer qualification. Not all VA loans or properties will qualify. Interest rates, loan balances, assumption costs, and equity requirements vary by transaction. This article is for educational purposes and is not financial or lending advice.
Angie McCormick
Broker/Owner | The McCormick Group
or another way